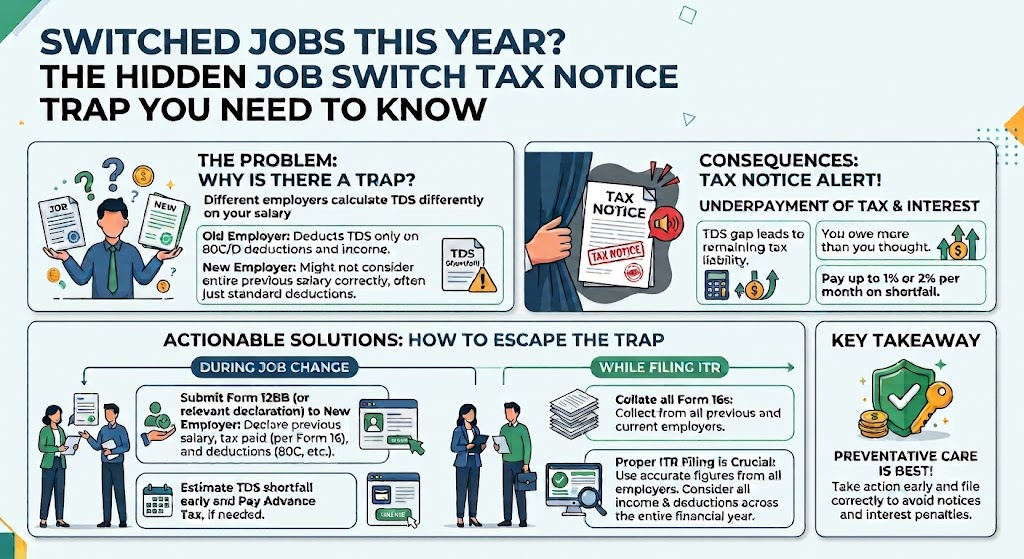
Got a big hike when you switched jobs last year? Before you celebrate, here’s a warning: many salaried employees who changed jobs mid-year are now facing an unexpected income tax notice this July even though both employers deducted TDS correctly. If you’re wondering why your tax liability suddenly jumped despite “perfect” TDS on both Form 16s, the answer lies in a quiet payroll mechanism most employees never hear about.
Why a Job Switch Can Suddenly Increase Your Tax Bill
We recently reviewed a case where the client had no income beyond salary and a small savings bank interest. Both Form 16s showed accurate TDS, with no hidden income or red flags anywhere. Yet at the time of filing, a significant tax demand appeared out of nowhere a textbook example of a job switch tax notice that catches even careful, fully compliant taxpayers off guard.
The Real Reason: Dual Slab Benefit Duplication
When you join a new employer mid-year, their payroll software typically starts your tax calculation fresh, based only on the salary they pay you from your joining date onward. The new employer unknowingly applies the basic exemption limit and the lower income tax slabs all over again even though your previous employer had already applied those exact benefits on your earlier salary.
How Payroll Systems Calculate TDS Independently
Each employer’s payroll engine works in isolation, with no visibility into what you earned before joining unless you inform it. Both employers, acting in good faith, apply slab benefits independently a “dual slab benefit” duplication that looks fine on paper during the year but unravels the moment your total income is aggregated at ITR filing. Your consolidated income then falls into a higher bracket, and the shortfall becomes a tax demand.
3 Rules to Avoid an Income Tax Notice After Changing Jobs
Key Takeaways: Preventing a Job Switch Tax Notice
TDS is only an estimate your final tax is computed on your global, consolidated income, not on a single employer’s payment.
Submit Form 12B to your new employer, declaring your previous salary and TDS, so tax is calculated on your correct combined income.
The math is rarely wrong the tax base often is. Verify Form 26AS and AIS before you file.
What to Do If You’ve Already Received a Tax Demand
Already received a demand? Don’t panic it’s correctable. Recompute your liability on the combined salary from both employers, pay the balance as self-assessment tax before filing, and keep both Form 16s handy. The Income Tax Department‘s e-filing portal lets you verify TDS credits through Form 26AS and the Annual Information Statement before you submit your return, reducing the chance of a mismatch notice.
As Dr. Haresh Adwani, a senior tax practitioner advising salaried professionals for decades, often notes that most “surprise” tax demands are not compliance failures at all they are structural gaps created by how independent payroll systems calculate tax in isolation.
Frequently Asked Questions
1.Why did I get a tax notice after switching jobs?
This usually happens due to dual slab benefit duplication, where two employers each apply the basic exemption and lower slabs independently. Aggregating both incomes at filing removes this duplication and raises your final tax.
2.What is Form 12B and why does it matter for a job switch tax notice?
Form 12B is a declaration of your previous employer’s salary and TDS, submitted to your new employer. It allows accurate, consolidated TDS deduction and helps prevent a mismatch-driven tax demand.
3.Can TDS deducted by both employers still result in a tax demand?
Yes. TDS is only an estimate based on each employer’s own payroll data. Your actual liability is computed on your total consolidated income once your ITR is filed.
Conclusion
A job switch tax notice is rarely about hidden income — it’s almost always about overlapping slab benefits from two payroll systems. Submitting Form 12B on time and reconciling your Form 26AS before filing can save you from an unpleasant surprise this tax season.
If you’ve changed jobs this year and want expert guidance on avoiding a tax demand, connect with itradvisor.in today for a professional review of your income and TDS position.
About the Author : Shreya Kavitke
Shreya Kavitke is a CA Finalist and an Article Assistant at Adwani & Co. LLP, where she works across diverse areas of taxation, accounting, and regulatory compliance. With a strong academic foundation in commerce and practical exposure to advisory and compliance engagements, she contributes to research and analysis on evolving tax and business regulations.
Her areas of interest include direct taxation, Goods and Services Tax (GST), corporate compliance, and financial reporting.
At ITRadvisor, Shreya contributes articles that combine technical accuracy with practical applicability, helping readers stay informed about key tax developments, compliance obligations, and emerging regulatory trends. She believes that clear, reliable, and timely guidance is essential to navigating today’s dynamic tax environment.
This version reflects the polished, research oriented tone commonly found in publications by leading professional services firms while remaining authentic to Shreya’s current role and experience.
Want clarity on Section 44AD, ITR-4 filing, or how to present your financials to creditors? Visit ITRAdvisor.in for expert-reviewed tax guidance, practical tools, and authoritative content designed for small business owners across India. Stay compliant. Stay financially aware.
At ITRAdvisor.in, we help taxpayers with:
✔️ ITR Filing Review
✔️ AIS Reconciliation
✔️ Capital Gains Reporting
✔️ NRI Taxation
✔️ Tax Notice Response
✔️ Revised Returns
✔️ Income Tax Planning
✔️ Refund and Compliance Issues
If you are unsure whether your return has been filed correctly or want a professional review before submission, consulting an experienced tax professional can help avoid costly mistakes.
Visit ITRAdvisor.in for expert assistance with your Income Tax Return and tax compliance requirements.
Disclaimer: ITRAdvisor.in is an educational and informational platform focused on tax awareness and compliance updates. Nothing contained herein should be construed as solicitation or advertisement of professional services. Professional services, where applicable, are rendered in accordance with ICAI guidelines. This article is published on ITRAdvisor.in, a tax and compliance knowledge platform. The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP
A prominent “File Your ITR Now” button near the top and again at the end of the article
Need help filing your Income Tax Return? Click the WhatsApp icon and our team will guide you through the process and assist you with your ITR filing.
Have questions about your ITR? Click the WhatsApp icon to connect with our tax experts for quick guidance and personalized assistance.
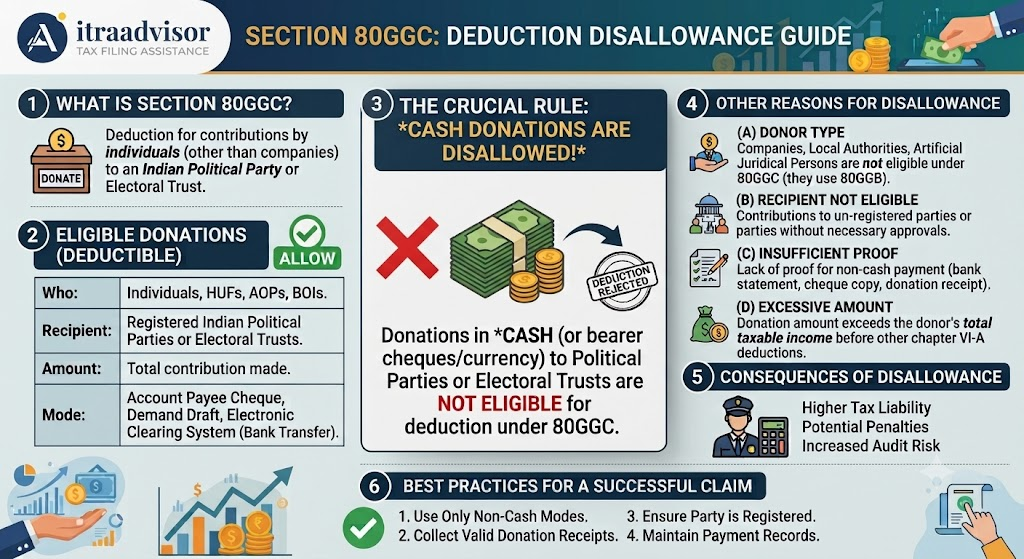
You donated money to a political party, claimed the Section 80GGC deduction in your Income Tax Return, and thought that was the end of it. Then one morning, a message from the Income Tax Department lands in your inbox your deduction has been flagged for scrutiny, and you are now asked to justify a claim worth lakhs of rupees. If this sounds alarming, it should. And it is happening to thousands of Indian taxpayers right now.
The Income Tax Department has significantly intensified scrutiny of Section 80GGC deductions in recent assessment cycles. Salaried professionals, business owners, and HUFs who claimed political donation deductions are receiving SMS alerts, scrutiny notices, and in some cases, full disallowance of their claims — with penalties that can reach 200% of the tax evaded. Yet, Section 80GGC is a completely legitimate, government-sanctioned provision that rewards transparent political funding with meaningful tax benefits.
The problem is not the section itself. The problem is how — and whether it has been used correctly. In this comprehensive guide, the expert team at Adwani and Company walks you through everything: what Section 80GGC actually allows, who qualifies, what conditions must be met, why deductions get disallowed, how to protect your claim, and what to do if you have already received a notice under this provision.
Whether you are filing your ITR 2026 for the first time with a political donation or are already facing scrutiny for a past claim, this is the guide you need to read fully, carefully, and right now.
What Is Section 80GGC? The Income Tax Deduction on Political Donations Explained Clearly
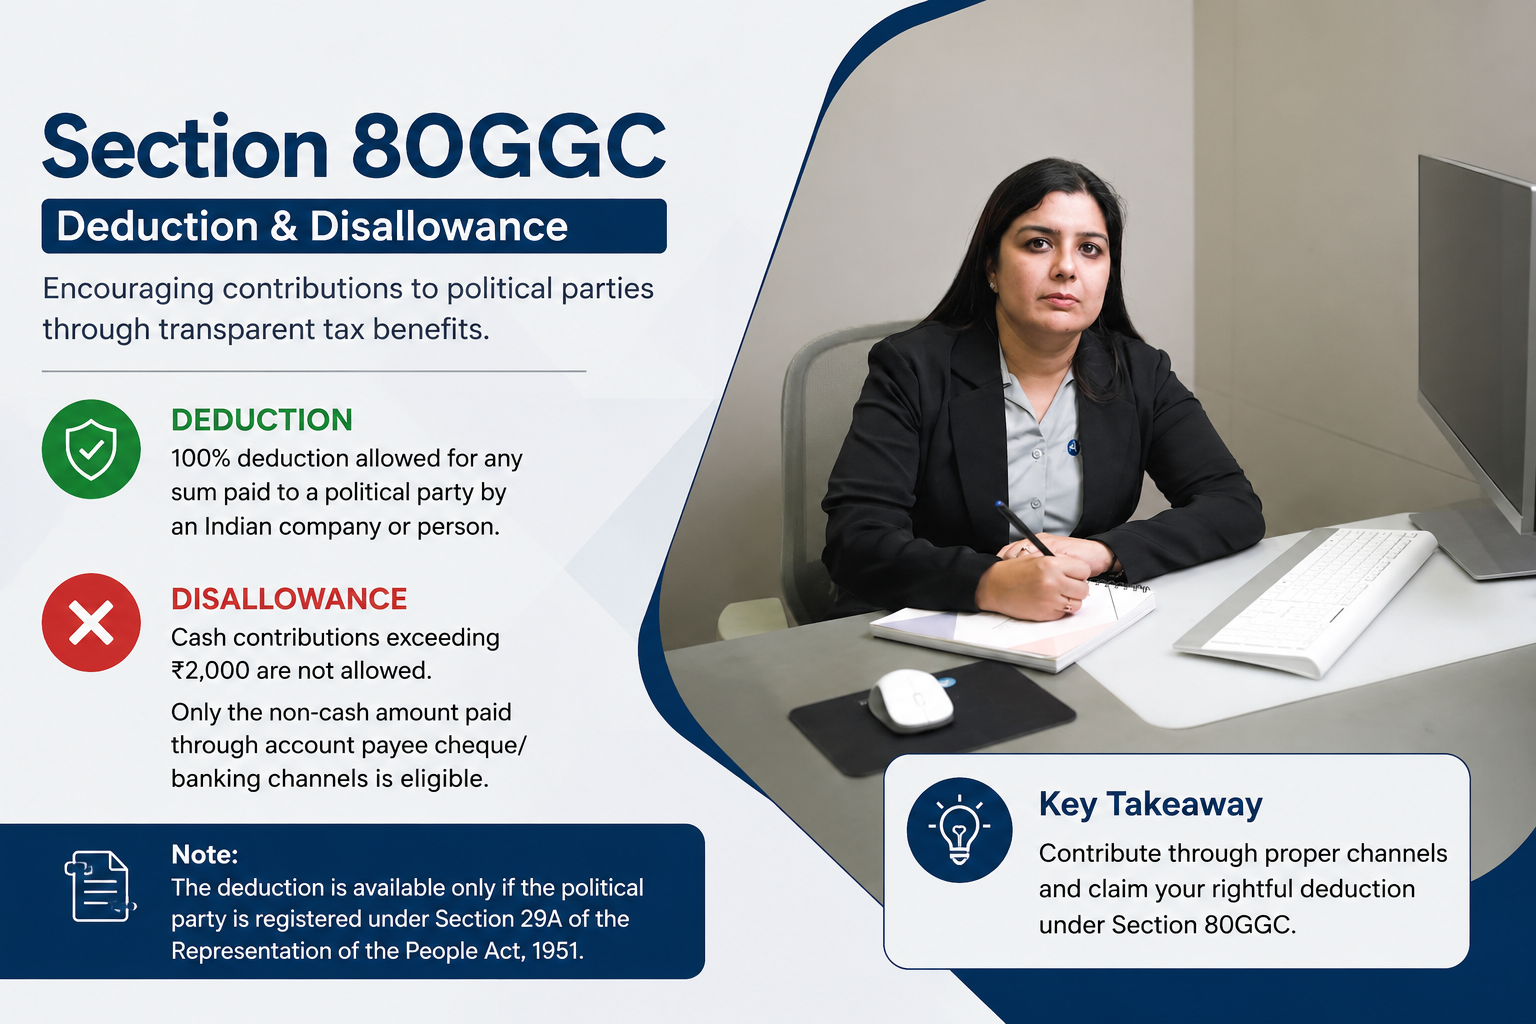
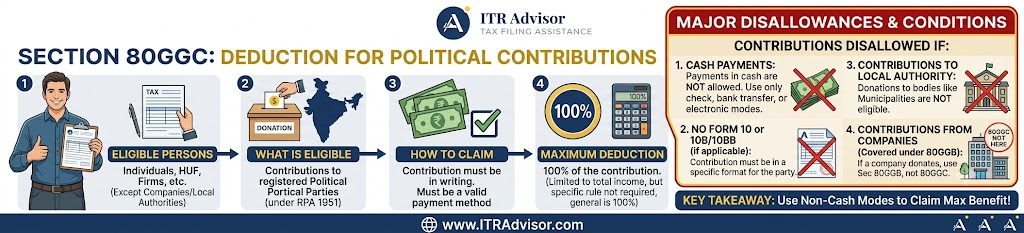
Section 80GGC of the Income Tax Act, 1961 now also reflected in the newly enacted Income Tax Act 2025 is a provision under Chapter VI-A that allows eligible taxpayers to claim a deduction for contributions made to registered political parties or approved electoral trusts. The deduction covers 100% of the amount donated, making it one of the most generous deductions available to individuals under Indian tax law.
The purpose of this section is rooted in democratic policy: to encourage transparent, traceable, and formally documented political funding. By providing a tax incentive for political contributions, the government aims to reduce unaccounted cash flowing into political campaigns and push donors toward legitimate, banking-channel-based contributions.
However, the very generosity of this deduction 100% of the donated amount with no fixed upper cap in rupee terms has made it a target for misuse, which is precisely why the Income Tax Department’s scrutiny of Section 80GGC claims has intensified dramatically in 2025 and 2026.
Section 80GGC vs. Section 80GGB : Key Differences You Must Know
Feature
Section 80GGB
Section 80GGC
Who can claim
Indian companies only
Individuals, HUFs, Firms, AOPs — NOT companies
Deduction limit
100% of donation
100% of donation (max = total taxable income)
Cash donations allowed?
No
No — banking channels mandatory
Tax regime
Old regime only
Old regime only
Mode of payment
Cheque, DD, banking channels
Cheque, DD, UPI, net banking, cards
As Dr. Haresh Adwani, Managing Partner at Adwani and Company, explains to clients: “Many taxpayers confuse 80GGC with 80GGB or assume companies can use this provision. They cannot. Section 80GGC is exclusively for non-corporate assessees. Allowing a company to claim under 80GGC is an error that will invite immediate disallowance.”
Who Is Eligible to Claim Section 80GGC Deduction? Eligibility Criteria for 2026
Before claiming this deduction in your ITR, verify that you meet each of the following conditions without exception:
Eligible Assessees Under Section 80GGC
Individual taxpayers : salaried, self-employed, professional, or retired
Hindu Undivided Families (HUFs)
Firms : partnership firms and LLPs
Association of Persons (AOP) and Body of Individuals (BOI)
Artificial juridical persons NOT wholly or partly funded by the government
Who is explicitly NOT eligible:
Indian companies they must claim under Section 80GGB instead
Local authorities and government-funded entities
Foreign entities or non-residents donating to Indian political parties
Eligible Recipients Where Must the Donation Go?
Your contribution must be made to one of the following:
A political party registered under Section 29A of the Representation of the People Act, 1951 verified by the Election Commission of India at eci.gov.in
An electoral trust approved under Section 13B of the Income Tax Act and notified by the CBDT
Donations to NGOs, social welfare organisations, independent candidates, or any party not registered with the Election Commission of India do not qualify and this is one of the most common triggers for disallowance.
Mode of Payment : Only Non-Cash Contributions Qualify
This is a hard, non-negotiable statutory rule. Cash donations are completely ineligible for Section 80GGC deduction. Only these modes are accepted:
Cheque or demand draft
Internet banking (NEFT / RTGS)
UPI transfer
Debit card or credit card
Wire transfer through legitimate banking channels
“The moment a client tells me they donated in cash or that a party arranged the receipt afterward, I know we have a serious problem. Cash donations are not just disallowed — they can trigger fraud allegations and penalties of up to 200%.” Adwani and Company
How to Claim Section 80GGC Deduction in Your ITR :Step-by-Step Process for 2026
Claiming the Section 80GGC deduction is straightforward if your contribution is genuine and well-documented. Here is the step-by-step process:
Step 1 : Verify party registration: Before making any contribution, confirm on eci.gov.in that the party is duly registered under Section 29A of the Representation of the People Act, 1951. Note the party’s PAN you will need it while filing.
Step 2 : Donate via banking channels only: Transfer the amount via cheque, bank transfer, UPI, or card. Retain your bank statement showing the debit. Never use cash or a middleman.
Step 3 : Obtain the official donation receipt: The political party must issue a formal receipt containing the donor’s name, donation amount, date, mode of payment, party PAN, and party TAN. This receipt is your primary evidence for claiming and defending the deduction.
Step 4 : Choose the old tax regime: Section 80GGC is unavailable under the new tax regime under new income tax rules April 2026. Your regime choice must be made at the time of filing.
Step 5 : Declare in the correct ITR field: Navigate to the Chapter VI-A deductions section of your ITR form and enter the Section 80GGC amount accurately, including party PAN and payment details.
Step 6 : Inform your employer (salaried taxpayers): Submit the donation proof to your employer so they can include it in Form 16 and adjust TDS. Discrepancies between Form 16 and your ITR are a common scrutiny trigger.
Step 7 : Preserve all documentation for 6 years: Receipts are not uploaded while filing but must be retained — the Income Tax Department can open scrutiny for up to 6 prior years.
Section 80GGC Deduction : A Practical Numerical Example
Mr. Arjun Mehta is a salaried professional in Mumbai with an annual gross total income of ₹12,00,000 for Financial Year 2025-26 (Tax Year 2025-26 under the Income Tax Act 2025 / AY 2026-27 under the older terminology). He donates ₹1,50,000 via UPI to a registered political party’s bank account and receives an official receipt with the party’s PAN and TAN.
Gross Total Income: ₹12,00,000
Section 80GGC Deduction Claimed: ₹1,50,000 (100% of donation fully deductible)
Taxable Income after deduction: ₹10,50,000
Approximate tax saved at 30% slab: ₹45,000
Effective cost of the donation to Mr. Mehta: ₹1,05,000 after tax benefit
Now contrast this with a problematic scenario: Mr. Vikram Shah donates ₹2,00,000 in cash to a local party that is not registered under Section 29A. He claims ₹2,00,000 under Section 80GGC. During scrutiny, the department finds the donation was cash-based and the party is unregistered. Result: full disallowance, the ₹2,00,000 added back to his income, and a penalty under Section 270A potentially ranging from ₹60,000 to ₹1,20,000 plus interest under Sections 234A, 234B, and 234C.
The difference between Mr. Mehta and Mr. Shah is not the amount donated — it is the process followed. Documentation and compliance are everything.
Section 80GGC Disallowance : Why the Income Tax Department Is Rejecting Claims in 2026
The Income Tax Department has made Section 80GGC one of its top scrutiny priorities. The CBDT and the department’s Investigation Wing have conducted coordinated searches on political parties and related entities, uncovering widespread misuse of this provision. Here are the core reasons deductions are being disallowed:
Reason for Disallowance
Risk Level
Consequence
Cash or kind donation
Very High
100% disallowance + penalty under Section 270A
Donation to unregistered party
Very High
Full disallowance no appellate relief
Missing receipt / party PAN
High
Deduction rejected at scrutiny stage
Donation exceeds total taxable income
Medium
Excess amount disallowed
Accommodation entry / fake donation
Extreme
Disallowance + 200% penalty + prosecution risk
Claimed under new tax regime
High
Deduction invalid added back to income
The Accommodation Entry Problem : What Every Donor Must Understand
In numerous cases across India, certain small or obscure registered political parties have been found operating as accommodation entry conduits. A taxpayer ‘donates’ money via bank transfer to such a party, receives a receipt, and the funds are routed back through intermediaries — minus a commission. The donor claims a 100% tax deduction while effectively retaining the money. This is structured tax fraud.
Courts including multiple ITATs and the CBDT have taken a firm stance: a Section 80GGC disallowance based on accommodation entry findings is legally valid even when the receipt exists and the payment was non-cash if the department can demonstrate that the donation was systematically layered and returned to the donor.
In a documented case, the Ahmedabad ITAT upheld the disallowance of ₹1,13,51,000 claimed as Section 80GGC deduction after establishing that the political parties involved used bank accounts for systematic fund layering and routing through intermediaries. The assessee could not rebut this evidence, and the deduction was denied in full.
What the Income Tax Department Is Actively Doing Right Now
As confirmed by tax practitioners and reported by CNBC-TV18, the Income Tax Department has sent SMS and email alerts to thousands of taxpayers who claimed Section 80GGC deductions in AY 2024-25 and AY 2025-26, asking them to verify and rectify their claims by filing an Updated ITR (ITR-U). The red flags that trigger scrutiny include:
Donation amounts disproportionately high relative to gross income (such as donating 40–50% of annual earnings)
Donations to political parties with no visible public activity, elections contested, or verifiable presence
Multiple taxpayers from the same organisation or locality claiming identical donation amounts to the same obscure party
Donations made through intermediaries rather than directly to the party’s officially registered bank account
Receipts lacking the party’s PAN, TAN, or official seal
How to Protect Your Section 80GGC Deduction Claim and Avoid Disallowance
If your claim is genuine, you have every right to defend it and with proper documentation and professional support, most genuine claims can be successfully protected. Here is what Adwani and Company recommend:
Verify party registration before donating: Check eci.gov.in to confirm the party is registered under Section 29A of the Representation of the People Act, 1951. Do this before transferring any money. Take a screenshot as evidence.
Maintain a complete paper trail: Your bank statement must show the exact amount debited on the exact date, to the party’s officially registered bank account. Keep this along with the donation receipt, party PAN, party TAN, and your ITR acknowledgment.
Never route through intermediaries: Make the transfer directly from your personal bank account to the party’s official account. Any middleman creates a legal vulnerability the department will exploit.
File correctly under the old tax regime: Confirm your regime choice before filing. Section 80GGC is unavailable under the new regime — claiming it while under the new tax regime results in automatic disallowance.
Act on ITD SMS alerts promptly: If you receive an SMS or email from the Income Tax Department questioning your Section 80GGC claim, consult a qualified CA immediately. Filing a voluntary Updated ITR (ITR-U) within one year attracts only 25% additional tax on the shortfall far less painful than waiting for a full scrutiny notice.
How Adwani and Company Helps Taxpayers Navigate Section 80GGC Claims and Notices
At Adwani and Company, Section 80GGC advisory both pre-filing guidance and post-notice defence is a core part of the firm’s income tax practice. Dr. Haresh Adwani and his specialist team work with individual taxpayers, HUFs, and business owners across India to ensure political donation claims are made correctly, defensibly, and in full compliance with the Income Tax Act 2025 and the latest CBDT guidelines.
If you have received a scrutiny notice, an SMS alert, or a proposed disallowance relating to your Section 80GGC claim, the team at Adwani and Company can:
Conduct a detailed legal review of your claim, documentation, and the department’s query
Assess whether the political party you donated to is at risk of accommodation entry classification
Prepare a comprehensive, legally sound written response to the Income Tax Department or Assessing Officer
Represent you before the AO, CIT(Appeals), or ITAT as required
Guide you on whether filing an Updated ITR is appropriate and financially advantageous
Advise on penalty mitigation strategies under Sections 270A and 271AAC
As Dr. Haresh Adwani notes: “A genuine claim, properly documented and professionally presented, stands up under scrutiny. The clients who face real damage are those who either made the donation incorrectly or responded to the notice without expert guidance. Both problems are entirely avoidable.”
Frequently Asked Questions About Section 80GGC Deduction and Disallowance
1: Is Section 80GGC available under the new tax regime 2026?
No. Section 80GGC is a Chapter VI-A deduction available only under the old tax regime. If you have opted for the new tax regime under the Income Tax Act 2025 or new income tax rules April 2026, you cannot claim this deduction. Claiming it while under the new regime leads to disallowance and interest.
2: What is the maximum deduction limit under Section 80GGC?
Section 80GGC allows a 100% deduction on the amount donated, with no fixed rupee upper cap. However, the total deduction cannot exceed your total taxable income for the year. Contributions beyond that amount will be partly disallowed.
4: What happens if my Section 80GGC deduction is disallowed?
The donated amount is added back to your taxable income, creating a higher tax demand. On top of the additional tax, you face interest under Sections 234A, 234B, and 234C, plus a penalty under Section 270A ranging from 50% to 200% of the under-reported tax. You retain the right to appeal the disallowance before CIT(Appeals) and ITAT.
FAQ 5: Can I claim Section 80GGC if I donate to an electoral trust?
Yes, provided the electoral trust is approved under Section 13B of the Income Tax Act and notified by the CBDT. Verify its approval status before donating. The same conditions apply non-cash payment, proper receipt, and filing under the old tax regime.
7: How is the Section 80GGC deduction different from Section 80C deduction?
Section 80C allows deductions for investments like PPF, ELSS, life insurance premiums, and home loan principal repayment capped at ₹1.5 lakh per year. Section 80GGC allows deductions specifically for political party donations with a 100% deduction and no fixed rupee cap. Both deductions are independent and can be claimed simultaneously under the old tax regime. Read our detailed guide on the Old Tax Regime Deductions List 2026 at itradvisor.in for a full comparison.
Conclusion : Section 80GGC Is Powerful, But Only When Used Correctly
Section 80GGC is not a problematic provision it is a powerful, legitimate tool for tax planning that simultaneously supports transparent political funding in India. The issue arises when it is misused, inadequately documented, or claimed without meeting the statutory conditions. In 2026, with the Income Tax Department actively scrutinising these claims and the CBDT empowered to issue compliance alerts to lakhs of taxpayers, the cost of getting this wrong has never been higher.
If your Section 80GGC claim is genuine made to a registered party, via banking channels, with a proper receipt, and declared under the old tax regime you have nothing to fear. A well-documented, professionally presented claim will withstand scrutiny. But if there are gaps in your process, acting quickly through a voluntary Updated ITR or a strong professional response to any notice received is far better than waiting.
Nidhi Adwani is the Human Resources Manager at Adwani & Co. She is a Law Graduate and holds an MBA in Human Resources. She manages recruitment, employee engagement, team development, workplace culture, and the firm’s social media and content activities. Passionate about people and organizational growth, she also contributes articles for ITRAdvisor and Adwani & Co. Her writing focuses on HR practices, leadership, workplace engagement, and professional development, offering practical insights for professionals and businesses.
At ITRAdvisor.in, we help taxpayers with:
✔️ ITR Filing Review
✔️ AIS Reconciliation
✔️ Capital Gains Reporting
✔️ NRI Taxation
✔️ Tax Notice Response
✔️ Revised Returns
✔️ Income Tax Planning
✔️ Refund and Compliance Issues
Visit ITRAdvisor.in today for professional guidance and consultation.
Early action can often prevent bigger tax problems later.
Disclaimer ITRAdvisor.in is an educational and informational platform focused on tax awareness and compliance updates. Nothing contained herein should be construed as solicitation or advertisement of professional services. Professional services, where applicable, are rendered in accordance with ICAI guidelines. This article is published on ITRAdvisor.in, a tax and compliance knowledge platform. The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP.
There is a version of the future that looks something like this: an AI model prepares your financial statements, flags every variance, models out three scenarios, and suggests a tax treatment all before your morning coffee. No analyst. No partner review. No judgment call required.
That version of the future is both closer than most people realise and more incomplete than most people expect.
Over the last several months, our team has spent meaningful time reviewing AI-generated outputs across financial modeling, accounting, tax analysis, and business performance reporting. The exercise has been instructive not because AI performed poorly, but because of precisely where it fell short. And it almost never fell short on the calculation.
The Calculation Is Not the Hard Part
Ask an AI model to build a discounted cash flow model, reconcile a set of accounts, or identify a variance between actuals and budget and it will typically do a competent job. The mechanics of finance: the formulas, the structures, the formats these are well within the capability of today’s AI tools.
What is harder to automate is the layer that sits above the calculation. The reasoning.
Where AI-Generated Finance Outputs Tend to Struggle
• Incorrect assumptions presented without qualification or disclosure
• Technically valid conclusions that are commercially or contextually wrong
• Reasoning that sounds authoritative but does not hold up under scrutiny
• Missing flags on transactions or entries that a practitioner would immediately question
• Tax treatments suggested without considering jurisdiction-specific nuance or recent regulatory changes
This is not a criticism of the technology. It is a structural observation. AI models are trained on patterns in data. Professional judgment is built on experience, context, and accountability. These are genuinely different things.
What Finance Professionals Judgment Actually Means in Finance
The term gets used loosely, but in practice, Financial professionals judgment in finance and accounting refers to a set of specific capabilities that go beyond technical execution.
Evaluating Whether Assumptions Are Reasonable
A financial model is only as good as the assumptions it is built on. An AI system can populate assumptions from historical data or industry benchmarks. It will rarely ask whether those benchmarks apply to this specific business, in this specific market, at this specific stage of its development. A finance professional will.
Connecting the Numbers to the Business Reality
When a variance analysis shows that gross margins have declined by 4 percentage points quarter-over-quarter, the calculation is straightforward. The professional question is: why, and does it matter? That requires knowing something about the business sits pricing model, its cost structure, its competitive position. The number is just the starting point.
Applying Judgment Under Regulatory and FinanceProfessional Standards
Tax treatments, accounting policies, disclosure requirements these are governed by frameworks like IFRS, US GAAP, the Income Tax Act, or IRS guidance. These frameworks require interpretation. The same transaction can be treated differently depending on facts and circumstances that a practitioner is trained to identify and evaluate. AI can surface the options. The professional makes the call.
Standing Behind the Work
Finance Professionals accountability matters. When a financial report is signed off, when a tax position is taken, when a valuation is presented to a board or an investor someone is professionally responsible for that output. That accountability structure does not transfer to an AI tool. It rests with the professional.
AI Capability vs. Professional Judgment: A Practical Comparison
What AI Does Well
Where Professional Judgment Is Needed
Data processing and structuring at scale
Evaluating whether the data is complete and reliable
Applying standard formulas and models
Questioning whether the model structure fits the situation
Identifying patterns and variances
Determining what those patterns mean for the business
Generating multiple scenarios quickly
Deciding which scenarios are realistic and commercially relevant
Drafting tax computations and analysis
Applying jurisdiction-specific judgment and regulatory interpretation
Producing formatted financial reports
Reviewing whether disclosures are adequate and positions are defensible
Flagging anomalies in large datasets
Knowing which anomalies require action and which do not
The Right Question Is Not Replacement: It Is Integration
The conversation in professional circles often frames AI as a threat to finance careers. After working closely with these tools across real client engagements, CA Manish Head Consultant for International Accounting and Financial Modeling at Adwani & Co LLP has consistently observed the opposite dynamic.
The better AI becomes at handling the mechanical layer of finance, the more visible the value of the professional judgment layer becomes. AI removes the excuse for spending most of your time on data entry, number-crunching, and report formatting. What is left the interpretation, the advisory, the structured thinking is precisely the work that creates value for clients.
The Most Effective Finance Teams We Work With Share One Common Pattern They use technology to eliminate repetitive, low-judgment work. They concentrate their best people on analysis, interpretation, and decision support. They treat AI outputs as a starting point for review not a finished product. They understand that speed and scale are AI’s advantage; judgment and accountability are theirs.
Practical Implications for Finance Professionals and Business Owners
Whether you are a CFO, a CA in practice, a finance team lead, or a business owner who works closely with financial data, the practical implications are similar.
For Finance Professionals
Develop the ability to critically evaluate AI-generated analysis, not just accept it
Invest in the interpretive and advisory skills that AI cannot replicate
Build workflows that combine AI efficiency with human review at decision-critical points
Stay current on regulatory changes this is an area where AI outputs can quickly become outdated or jurisdiction-specific errors can slip through
For Business Owners and Founders
Do not mistake a well-formatted AI output for a professionally reviewed one presentation and accuracy are different things
Ensure there is a qualified professional accountable for the financial work, regardless of the tools being used
Use AI to get faster, more frequent visibility into your numbersbut invest in the advisory relationship that helps you act on what you see
When significant decisions fundraising, restructuring, cross-border transactions, tax positions are on the table, professional review is not optional
• AI performs well on the mechanical and computational layer of finance data structuring, model building, report generation, variance identification.
• The gap between AI outputs and professionally reliable conclusions is most apparent in reasoning: assumptions, interpretation, regulatory judgment, and accountability.
• Finance Professionals judgment in finance is built on experience, context, and professional accountability qualities that cannot be automated.
• The most effective approach combines AI’s scale and speed with a human professional’s interpretive and advisory capability.
• For significant financial decisions, professional review remains non-negotiable regardless of the tools being used.
• The future of finance is not AI versus professionals it is AI and professionals, each contributing what they do best.
Frequently Asked Questions
1. Can AI tools replace a CA or CPA for tax filing and financial reporting?
Not reliably. AI tools can assist with data processing, computation, and draft preparation, but tax filings and financial reports carry professional responsibility. A qualified CA or CPA applies judgment to regulatory interpretation, jurisdiction-specific rules, and disclosure adequacy in ways that AI cannot replicate or be held accountable for.
2. What is the biggest limitation of AI-generated financial models?
The most significant limitation is not technical accuracy in the calculations it is the assumptions. AI models will build on available data without always questioning whether the inputs are appropriate for a specific business or situation. A finance professionals reviews both the structure of the model and the reasonableness of the assumptions driving it.
3. How should a business owner use AI in their financial workflow?
AI works well for routine bookkeeping, data extraction, report formatting, and preliminary analysis. For anything involving decision-making, tax positions, investor reporting, or compliance, it should be treated as a first draft that a qualified professional reviews. Think of it as a capable analyst useful, but not the final word.
4. Will AI change what skills are valuable for finance professionals?
Yes, significantly. Finance Professionals who build strong interpretive, advisory, and judgment-based skills will find AI increases their capacity and reach. Those who have primarily relied on technical execution of routine tasks will need to adapt. The premium on analytical thinking, client advisory, and structured reasoning is increasing not decreasing.
5. Does Adwani & Co LLP use AI tools in its advisory and accounting work?
Yes. Our team actively integrates AI-assisted tools in financial analysis, modeling, and reporting workflows. The difference is that every significant output is reviewed by a qualified professional before it informs a client decision or compliance filing. Technology improves our throughput; professional judgment governs our outputs
Conclusion
The arrival of capable AI tools in finance and accounting does not reduce the value of Finance Professionals expertise it sharpens the focus on where that expertise actually lives. The calculation has never been the hard part. The hard part is knowing whether the reasoning behind the calculation is correct, whether the assumptions are defensible, and whether the conclusion will hold up when it matters.
That combination AI handling scale and efficiency, professionals providing judgment and accountability is where finance advisory is heading. And for businesses navigating complex financial decisions, tax positions, or cross-border reporting obligations, having a qualified professional in that chain is not a legacy requirement. It is a structural necessity.
Work With Adwani & Co LLP
If your business is looking to build stronger financial systems, improve reporting visibility, or benefit from professional review of AI-assisted analysis, the team at Adwani & Co LLP would be happy to connect.
We support clients across financial modeling, Virtual CFO advisory, international accounting, bookkeeping systems, and cross-border tax combining modern tools with qualified professional judgment. Explore our services: Virtual CFO Services | Financial Reporting & MIS Support | International Accounting & Advisory | QuickBooks & Xero Bookkeeping
Author CA. Manish R. Mata Practising In India (Ex – PwC), At Adwani & Co LLP leads the International Accounting & Tax Support vertical, delivering structured execution assistance to US CPA firms and overseas businesses.
Disclaimer
Adwani & Co LLP is a multi-disciplinary professional services platform. The blogs shared are for educational and informational purposes only and are intended to promote awareness around finance, accounting, taxation, reporting, and business advisory topics. Nothing contained herein should be construed as solicitation or advertisement of professional services. Where professional services are required under applicable laws or regulations, such services are rendered in accordance with relevant professional and regulatory requirements. The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP.
You paid GST under Reverse Charge Mechanism (RCM) on time. Good. But did you also issue a self-invoice for that RCM transaction? If not, your ITC claim and your audit file may already be at risk.
Many businesses treat RCM as a payment obligation and stop there. In reality, a self-invoice for RCM is a separate, mandatory document and skipping it is one of the most common GST compliance gaps we see at ITRAdvisor.in.
What Is a Self-Invoice for RCM?
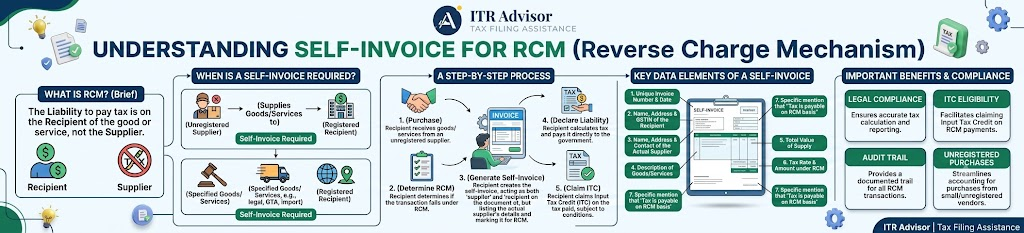
Under Section 31(3)(f) of the CGST Act, when a registered person receives taxable goods or services from an unregistered supplier and is liable to pay GST under RCM, the recipient not the supplier must issue the invoice. This is the self-invoice for RCM. It exists because an unregistered supplier cannot legally issue a GST-compliant tax invoice, so the law shifts that responsibility to you.
Why the Self-Invoice for RCM Actually Matters
It supports the GST you paid in cash under RCM.
Without it, you cannot claim ITC on that RCM payment under Rule 36(1)(b).
It strengthens your documentation trail during GST audits and scrutiny.
It closes a gap officers routinely check, since RCM leaves no supplier-side trail.
The 30-Day Deadline Most Businesses Miss
Since Rule 47A took effect on 1st November 2024, a self-invoice for RCM must be issued within 30 days of receiving the goods or services not at month-end, and not whenever convenient. Miss this window and you risk interest on delayed tax and penalty exposure under Section 122, on top of ITC disputes.
The self-invoice must also be reported in Table 13 of GSTR-1, paired with a payment voucher under Section 31(3)(g) when payment is actually made to the unregistered supplier.
Common Self-Invoicing Mistakes Under RCM
Paying RCM tax correctly but never generating the self-invoice.
Issuing it weeks late, well outside the 30-day window.
Not labelling it clearly as a self-billed invoice.
Forgetting the accompanying payment voucher.
Key Takeaways
A self-invoice for RCM is mandatory under Section 31(3)(f) whenever you buy from an unregistered supplier under reverse charge.
You must issue it within 30 days of receipt, under Rule 47A.
No self-invoice generally means no valid ITC claim on that RCM payment.
Frequently Asked Questions on Self-Invoice for RCM
1. Is a self-invoice for RCM always required?
Yes, whenever you’re liable to pay GST under RCM on a supply from an unregistered supplier.
2. What happens if I don’t issue a self-invoice for RCM?
You may lose your ITC claim on that RCM payment and face questions during a GST audit.
3. What is the deadline to issue a self-invoice under RCM?
Within 30 days of receipt, as mandated by Rule 47A effective 1st November 2024.
4. Is a payment voucher the same as a self-invoice?
No. The self-invoice records the supply; the payment voucher separately records the payment.
Conclusion: Don’t Let Paperwork Undo Correct Tax Payment
Paying GST under RCM is only half the compliance story. Issuing a proper, timely self-invoice for RCM is what protects your ITC, your audit trail, and your peace of mind. As Dr. Haresh Adwani, founding expert at Adwani & Co LLP, often points out, GST compliance is not just about depositing tax it is about proving that tax was correctly deposited, with the right document, at the right time.
Learn more about our GST Compliance Checklist 2026, or read our detailed guide on GST Input Tax Credit Rules 2026.
Nidhi Adwani is the Human Resources Manager at Adwani & Co. She is a Law Graduate and holds an MBA in Human Resources. She manages recruitment, employee engagement, team development, workplace culture, and the firm’s social media and content activities. Passionate about people and organizational growth, she also contributes articles for ITRAdvisor and Adwani & Co. Her writing focuses on HR practices, leadership, workplace engagement, and professional development, offering practical insights for professionals and businesses.
At ITRAdvisor.in, we help taxpayers with:
✔️ ITR Filing Review
✔️ AIS Reconciliation
✔️ Capital Gains Reporting
✔️ NRI Taxation
✔️ Tax Notice Response
✔️ Revised Returns
✔️ Income Tax Planning
✔️ Refund and Compliance Issues
Visit ITRAdvisor.in today for professional guidance and consultation.
Early action can often prevent bigger tax problems later.
Disclaimer ITRAdvisor.in is an educational and informational platform focused on tax awareness and compliance updates. Nothing contained herein should be construed as solicitation or advertisement of professional services. Professional services, where applicable, are rendered in accordance with ICAI guidelines. This article is published on ITRAdvisor.in, a tax and compliance knowledge platform. The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP.
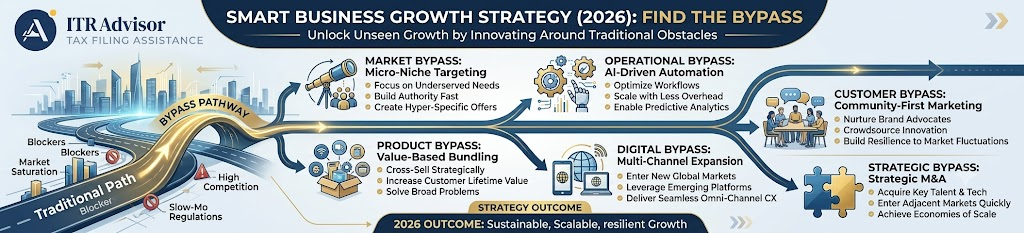
Smart Business Growth Strategy: Stop Pushing Harder and Find the Bypass
Here is a truth that most business owners learn too late: the biggest obstacle to growth is almost never what you think it is. You blame the sales team. You blame the market. You blame the economy. But the real problem the one quietly draining your revenue, your margins, and your energy is usually hiding in plain sight, disguised as something you have always accepted as normal.
The most effective smart business growth strategy is not about pushing harder through obstacles. It is about finding the bypass the smarter, faster, less crowded path that everyone else overlooked.
At Adwani and Company, we see this pattern repeatedly. Businesses generating ₹50 crore, ₹100 crore, or more in revenue come to us frustrated. Growth has stalled. Costs are rising. Customers are complaining. And the owner is convinced the solution is more effort, more investment, more pressure.
It rarely is.
In this blog, we will explore why the most powerful smart business growth strategy often involves subtraction, not addition removing the hidden friction points that silently sabotage your business. We will share a real-world example, actionable frameworks, and the thinking that seat separates businesses that scale from businesses that struggle.
Why Pushing Harder Is Not a Smart Business Growth Strategy
There is a deeply ingrained belief in Indian business culture that success comes from relentless effort. Work longer hours. Hire more salespeople. Spend more on marketing. Push, push, push.
And effort absolutely matters. Nobody builds a successful business without hard work.
But here is the problem: effort without direction is just friction. And friction, compounded over months and years, destroys businesses.
Consider this scenario. You are walking briskly one morning clear mind, strong focus, productive energy. Then you encounter a group blocking your path. Moving slowly. Chatting casually. Unaware of anyone behind them.
You have three options:
Wait behind them patient, but slow.
Force your way through aggressive, but creates conflict.
Find a side lane a simple bypass that gets you ahead without friction.
Option three is almost always the best choice. And it is almost always the one people overlook.
Business works the same way. The most effective smart business growth strategy is not about exerting more force against the same obstacle. It is about recognising the obstacle for what it is and finding a smarter route around it.
The Hidden Bottleneck: A Real-World Business Growth Strategy Example
Let us look at a situation that Dr. Haresh Adwani and the advisory team at Adwani and Company encountered with a client a mid-sized manufacturing business with annual revenue exceeding ₹50 crore.
The Symptoms
The business was showing classic signs of stagnation:
Revenue growth had slowed to near zero.
Customer complaints were increasing quarter over quarter.
Gross margins were shrinking despite stable pricing.
The operations team was working harder but achieving less.
The owner was convinced the problem was sales. “We need more customers. We need a better sales team. We need to spend more on marketing.”
The Diagnosis
When we looked deeper beyond the P&L statement and into the operational mechanics a different picture emerged.
The root cause was not sales. It was one supplier.
This supplier was well-known in the market. Popular. In demand. Every manufacturer wanted to work with them. And because of that dominant position:
Prices kept rising 8–12% annually, far above market averages.
Deliveries kept slipping lead times had grown from 2 weeks to 6 weeks.
Quality became inconsistent rejection rates had doubled in 18 months.
The business was haemorrhaging money, not because of a sales problem, but because of a supplier dependency problem. More than ₹50 crore in annual revenue was being exposed to decisions made by someone else’s business.
The Bypass
Instead of renegotiating harder (pushing through the crowd), we helped the client find the bypass.
We conducted a comprehensive supplier review evaluating alternatives across quality, pricing, delivery reliability, and scalability. The result was a newer, less crowded supplier that offered:
15% lower pricing on key raw materials.
60% faster delivery times from 6 weeks back to under 2 weeks.
Significantly better quality consistency rejection rates dropped by 70%.
The shift looked small on paper. One supplier changed.
The impact was anything but small:
Metric
Before Bypass
After Bypass
Raw material cost
₹18.5 crore/year
₹15.7 crore/year
Average delivery time
6 weeks
1.5 weeks
Quality rejection rate
8.2%
2.4%
Customer complaints
45/month
12/month
Revenue growth (next 12 months)
~0%
18%
That is the power of a well-executed business growth strategy not more effort, but better decisions.
Pattern Recognition: The Core of Every Great Business Growth Strategy
Warren Buffett does not succeed because he works harder than other investors. He succeeds because he sees patterns others miss. Steve Jobs did not build Apple by outspending competitors. He built it by recognising what customers wanted before they knew they wanted it.
The best smart business growth strategy is rooted in pattern recognition the ability to look at a complex business and identify the one lever that, when pulled, unlocks disproportionate results.
As Dr. Haresh Adwani often explains: “Numbers tell you what is happening. Patterns tell you why. And understanding why is where real advisory value begins.”
Most business owners are drowning in data. Revenue reports, expense dashboards, sales funnels, customer analytics. But data without interpretation is noise. The role of a strategic advisor is to cut through that noise and find the signal the one insight that changes the trajectory.
Five Signs Your Business Needs a Bypass, Not More Effort
How do you know when pushing harder is the wrong approach? Here are five patterns we frequently identify at Adwani and Company:
1. Revenue Is Growing but Margins Are Shrinking
If your top line is increasing but your bottom line is flat or declining, you have a structural problem not a sales problem. The bypass might be in your cost structure, your pricing model, or your customer mix.
2. Your Best People Are Burning Out
When high performers start leaving or disengaging, it is rarely about compensation. It is usually about friction inefficient processes, unclear priorities, or systemic bottlenecks that make their work unnecessarily difficult. The bypass is operational, not motivational.
3. Customer Complaints Are Increasing Despite Good Products
This almost always points to a supply chain or delivery issue. Your product may be excellent, but if it arrives late, arrives damaged, or arrives inconsistently, customers will leave. The bypass is upstream, not downstream.
4. You Are Over-Dependent on One Supplier, One Client, or One Channel
Concentration risk is the silent killer of mid-sized businesses. If more than 30% of your revenue or supply chain depends on a single entity, you are one decision away from crisis. The bypass is diversification systematic, strategic, and planned.
5. You Keep Solving the Same Problems
If the same issues resurface every quarter cash flow crunches, inventory mismatches, compliance delays you are treating symptoms, not causes. The bypass requires going deeper and restructuring the root process.
How to Build a Smart Business Growth Strategy Around Finding Bypasses
Here is a practical framework that any business owner can implement:
Step 1: Map Your Friction Points
List every area where your business experiences recurring delays, cost overruns, or quality issues. Be brutally honest. Common areas include procurement, logistics, compliance, hiring, and collections.
Step 2: Quantify the Cost of Friction
For each friction point, estimate the annual cost in money, time, and opportunity. You will be surprised how much “accepted” inefficiency is actually costing you. A ₹50 crore business can easily be losing ₹3–5 crore annually to friction it has never measured.
Step 3: Identify the Biggest Lever
Not all friction points are equal. Find the one that, if resolved, would have the largest cascading impact on revenue, margins, and customer satisfaction. This is your primary bypass.
Step 4: Explore Alternatives Relentlessly
Do not accept the first alternative you find. Evaluate multiple options. Test small before committing large. The best business growth strategy decisions are informed, not impulsive.
Step 5: Execute and Measure
Implement the change, track the metrics, and iterate. A bypass is not a one-time fix it is a new path that needs to be maintained and optimised over time.
The Role of Advisory in Modern Business Growth Strategy
Here is something most business owners do not want to hear: you cannot see your own blind spots.
You are too close to the business. You have too many emotional attachments to existing relationships, processes, and decisions. The supplier who is costing you ₹3 crore a year might also be someone you have known for 15 years. The process that is bleeding efficiency might be one you designed yourself.
This is where external advisory becomes invaluable not to replace your judgment, but to complement it with objectivity.
At Adwani and Company, our advisory approach goes beyond spreadsheets and compliance. Led by Dr. Haresh Adwani, our team works with business owners to identify hidden friction, quantify its impact, and design practical solutions that drive measurable growth.
Whether it is a supplier review, a cost restructuring, a compliance overhaul, or a full strategic reassessment, the goal is always the same: find the bypass that unlocks your next phase of growth.
The Ministry of Corporate Affairs (MCA) and regulatory frameworks like the Companies Act increasingly demand that businesses maintain robust governance and operational structures. A strong business growth strategy must account for compliance as a growth enabler, not just a cost centre.
Frequently Asked Questions
1. What is a smart business growth strategy?
A business growth strategy is a structured plan to increase revenue, improve margins, and scale operations sustainably. It involves identifying opportunities, removing bottlenecks, and making strategic decisions about markets, products, pricing, and operations.
2. Why does pushing harder sometimes fail as a business growth strategy?
Because effort without direction creates friction. If the underlying problem is structural a bad supplier, an inefficient process, a flawed pricing model more effort will not solve it. You need to identify and address the root cause.
3. How do I identify hidden bottlenecks in my business?
Start by mapping every area where recurring problems occur delays, cost overruns, complaints, rework. Quantify the cost of each. The largest hidden cost is usually your biggest bottleneck and your most valuable bypass.
4. How often should a business review its growth strategy?
At minimum, annually. However, high-growth businesses benefit from quarterly strategic reviews. Market conditions, supplier dynamics, and customer needs change constantly your business growth strategy must evolve accordingly.
5. Can a single supplier really impact business growth?
Absolutely. As our real-world example demonstrated, one over-relied-upon supplier can silently erode margins, delay deliveries, and damage customer relationships putting crores of revenue at risk.
Conclusion: The Smartest Business Growth Strategy Is Seeing What Others Miss
Every business owner faces crowded paths saturated markets, rising costs, difficult suppliers, demanding customers. The instinct is to push harder, move faster, and outwork the competition.
But the most successful businesses the ones that scale sustainably and profitably do something different. They pause. They observe. They find the bypass.
The side lane nobody noticed. The supplier nobody evaluated. The process nobody questioned. The insight nobody connected.
That is not laziness. That is strategic intelligence. And it is the foundation of every truly effective business growth strategy.
Where in your business are you pushing harder when you should be looking for the bypass?
If you want expert guidance to identify hidden growth opportunities, streamline operations, and build a business growth strategy that actually works, connect with Adwani and Company today. Dr. Haresh Adwani and our advisory team are ready to help you find the path that transforms your business.
Author CA. Manish R. Mata Practising In India (Ex – PwC), At Adwani & Co LLP leads the International Accounting & Tax Support vertical, delivering structured execution assistance to US CPA firms and overseas businesses.
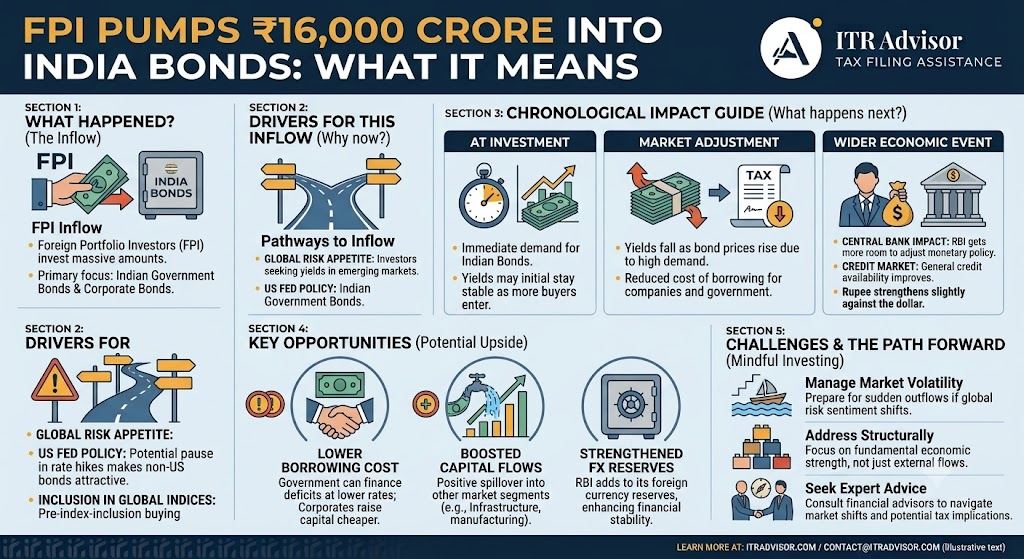
₹16,000 crore. One month. From foreign investors. That’s the scale of FPI investment flowing into Indian government bonds in June 2026 and it’s not noise. It’s a signal worth decoding.
If you’ve been tracking stock markets while ignoring the bond market, you may be missing the bigger story. FPI investment in India government bonds has surged to approximately US$1.84 billion in June 2026 alone making this one of the strongest monthly debt market inflows India has seen in over a year.
April and May together saw relatively modest foreign participation. June changed the conversation. The question every informed investor and taxpayer should be asking: why now, and what does it mean for you?
FPI Investment in India Government Bonds: What the Data Says
The India bond market inflows for June 2026 tell a compelling story. Foreign portfolio investors including global pension funds, sovereign wealth funds, and asset managers have collectively committed US$1.84 billion to Indian government securities (G-Secs) in the first half of June alone.
This isn’t reactive trading. Institutional investors of this scale make decisions months in advance, based on macroeconomic fundamentals, policy signals, and long-term return expectations.
June 2026 FPI Bond Inflow Snapshot
Total inflow: ~₹16,000 crore (US$1.84 billion)
Period: First half of June 2026
Context: One of the highest monthly inflows in 12+ months Comparison: Exceeds combined April + May 2026 inflows
Why FPI Investment in India Government Bonds Is Rising
Three structural forces are working together to drive this surge and understanding them helps you read the broader economic picture.
1. India’s Entry Into the JPMorgan EM Bond Index
India’s phased inclusion in JPMorgan’s Emerging Market Government Bond Index has been the single biggest catalyst for sustained FPI investment in Indian G-Secs. Index-tracking funds globally are now obligated to hold a proportion of Indian government bonds. This creates structural, non-discretionary demand not sentiment-driven flows that reverse with headlines.
2. RBI’s Fully Accessible Route (FAR)
The Reserve Bank of India introduced the Fully Accessible Route (FAR), allowing foreign investors to purchase specified Indian government securities without any investment ceiling. According to the RBI’s official FAR framework, this route significantly simplifies foreign access to India’s sovereign debt market removing the friction that previously deterred large institutional allocations.
3. India’s Macroeconomic Stability in a Volatile World
In 2026, global markets are navigating uncertainty elevated debt levels in developed economies, sticky inflation in parts of Europe, and geopolitical tensions. Against this backdrop, India’s macroeconomic stability is a genuine differentiator. Controlled inflation, robust forex reserves, and consistent GDP growth projections make India bond market inflows a rational, not just sentimental, choice for global capital.
As noted in frameworks aligned with India’s Ministry of Finance economic assessments, sustained foreign participation in the debt market supports efficient government borrowing, strengthens rupee stability, and improves India’s standing in global capital markets.
FPI Investment in India Bonds: What It Means for Indian Taxpayers
This isn’t just a market story. FPI bond inflows have direct downstream effects on Indian taxpayers and investors effects that rarely make the financial headlines but matter enormously for planning.
Lower bond yields over time → lower interest rates across the economy → cheaper home loans and business credit
Rupee support from FPI inflows → lower imported inflation → moderate impact on your cost of living
Positive sentiment spill-over → often precedes equity market confidence → relevant for your LTCG & STCG on mutual funds and shares
Improved government fiscal position → greater scope for tax relief or infrastructure spending in future budgets
For investors holding government bonds or bond mutual funds: the tax treatment remains unchanged. Interest income from G-Secs is taxable at your applicable slab rate. Capital gains on selling before maturity attract STCG (at slab rate) or LTCG (12.5% without indexation), depending on whether the holding period exceeds 24 months.
The Real Opportunity: Understanding Capital Flows, Not Just Markets
As Dr. Haresh Adwani PhD in Commerce and law graduate puts it: major financial decisions are shaped by economic fundamentals and long-term policy expectations, not daily market noise. The ₹16,000 crore in FPI investment in India government bonds is not a reaction to a single headline. It is the result of months of macroeconomic analysis by some of the world’s most sophisticated institutional investors.
For Indian taxpayers, business owners, and individual investors, the real opportunity lies in understanding the ‘why’ behind capital flows and calibrating your financial decisions accordingly. Is your fixed-income allocation positioned for a potentially declining yield environment? Is your advance tax planning aligned with the broader economic cycle? These are the questions that compound over time. For NRI investors navigating India’s debt market, there are additional FEMA compliance considerations.
Key Takeaways
Foreign investors invested ~₹16,000 crore (US$1.84B) in India government bonds in June 2026 alone among the highest monthly inflows in over a year.
India’s inclusion in JPMorgan’s EM Bond Index is creating structural, recurring demand for Indian G-Secs from global index funds.
The RBI’s Fully Accessible Route (FAR) removes investment ceilings for FPIs on specified government securities.
For Indian taxpayers, rising FPI bond inflows can signal lower future interest rates affecting home loans, business credit, and fixed-income returns. Understanding capital flows is as strategically important as tracking daily stock market indices.
Frequently Asked Questions
Q1: What is FPI investment in India government bonds?
FPI (Foreign Portfolio Investment) in India government bonds refers to overseas institutional investors pension funds, sovereign wealth funds, asset managers buying Indian government securities (G-Secs). These flows affect bond yields, borrowing costs, and the Indian rupee.
Q2: Why are foreign investors buying Indian government bonds in 2026?
Key drivers include India’s inclusion in JPMorgan’s EM Bond Index, the RBI’s Fully Accessible Route (FAR) removing investment caps, attractive yield premium over US Treasuries, and India’s macroeconomic stability with controlled inflation and strong forex reserves.
Q3: How does FPI bond investment affect Indian taxpayers?
Large FPI inflows into bonds can gradually lower yields reducing borrowing costs on home loans and business credit. Stable bond markets also support a stronger rupee, which affects import costs and inflation factors that indirectly influence your tax planning.
Q4: Is interest or gain from Indian government bonds taxable?
Yes. Interest income from G-Secs is taxable as income from other sources per your income tax slab. Capital gains on selling government bonds before maturity attract STCG (at slab rate) or LTCG (12.5% post-Budget 2024) depending on the holding period
Q5: Where can I track FPI investment flows in India bonds?
SEBI’s official FPI data dashboard and NSDL’s FPI tracker publish weekly and monthly debt/equity inflow data. The Reserve Bank of India’s monthly bulletin also reports capital flow trends in India’s debt market.
Conclusion: FPI Bond Inflows Are a Macro Signal : Know What to Do
The ₹16,000 crore FPI investment in India government bonds in June 2026 is more than a market statistic. It reflects a structural shift in global investor confidence toward India’s debt market — driven by index inclusion, improved market access, and macroeconomic credibility.
For Indian taxpayers and investors, it’s a reminder that the bond market is not a sideshow. Understanding capital flows is as strategically important as tracking your portfolio. And when FPI sentiment improves, it often creates downstream benefits — in interest rates, rupee stability, and fiscal space — that eventually reach your EMI, your returns, and your tax planning.
Stay informed. Stay ahead.
About the Author : Prafull Nile
Prafull Nile is a senior taxation and accounting professional associated with Adwani & Co LLP, bringing over 19 years of extensive experience in direct taxation, tax audits, income tax assessments, GST audits, and financial statement finalization. He has successfully managed diverse client engagements across industries, providing strategic guidance on tax compliance, assessments, and regulatory matters. In addition to his technical expertise, Prafull leads and mentors teams, ensuring high standards of service delivery and operational excellence. His practical approach, deep understanding of tax laws, and commitment to client success make him a trusted advisor for businesses and professionals navigating complex financial and compliance requirements.
At ITRAdvisor.in, we help taxpayers with:
✔️ ITR Filing Review
✔️ AIS Reconciliation
✔️ Capital Gains Reporting
✔️ NRI Taxation
✔️ Tax Notice Response
✔️ Revised Returns
✔️ Income Tax Planning
✔️ Refund and Compliance Issues
If you are unsure whether your return has been filed correctly or want a professional review before submission, consulting an experienced tax professional can help avoid costly mistakes.
Visit ITRAdvisor.in for expert assistance with your Income Tax Return and tax compliance requirements.
Disclaimer: ITRAdvisor.in is an educational and informational platform focused on tax awareness and compliance updates. Nothing contained herein should be construed as solicitation or advertisement of professional services. Professional services, where applicable, are rendered in accordance with ICAI guidelines. This article is published on ITRAdvisor.in, a tax and compliance knowledge platform. The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP
A prominent “File Your ITR Now” button near the top and again at the end of the article
Need help filing your Income Tax Return? Click the WhatsApp icon and our team will guide you through the process and assist you with your ITR filing.
Have questions about your ITR? Click the WhatsApp icon to connect with our tax experts for quick guidance and personalized assistance.
A senior employee once shared the news with quiet pride: “My company has granted me ESOPs worth ₹50 lakh.” The excitement was real. The number was real. But the tax problem lurking behind it? Completely invisible to them. If you hold ESOPs and haven’t thought about ESOP tax implications in India 2026, you may be walking straight into an unexpected tax liability one that arrives before a single rupee lands in your bank account.
What Are ESOPs and Why Does the Tax Timing Matter?
Employee Stock Option Plans (ESOPs) are a popular component of compensation packages across Indian startups and MNCs alike. They give employees the right to purchase company shares at a pre-determined price (the exercise price) at a future date.
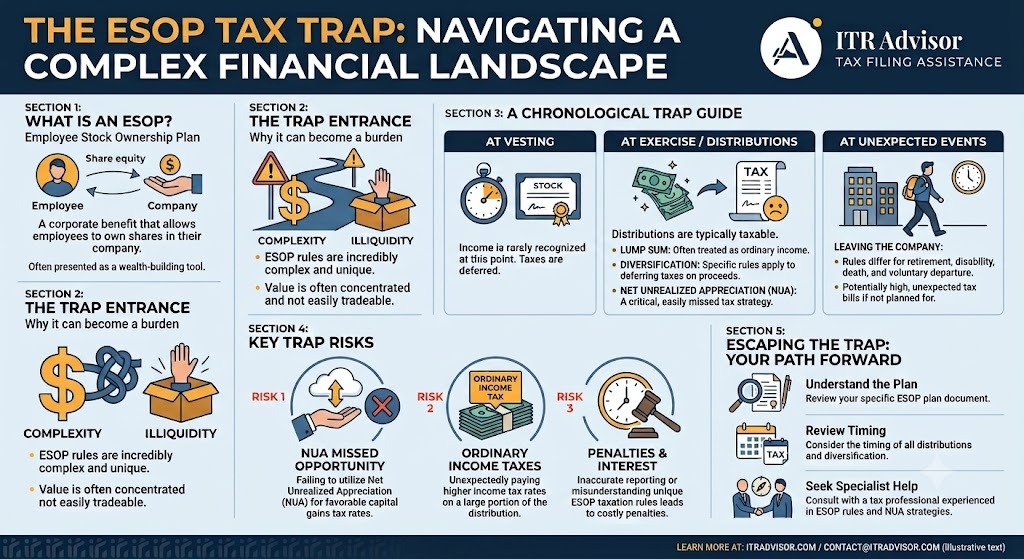
The critical issue with ESOP taxation in India is not whether you will be taxed you will be but when, and on how much. Most employees focus on the grant letter figure and miss the two separate tax events that can arise.
Stage 1: Tax at the Time of Exercise The Perquisite Trap
This is where most ESOP holders are blindsided. Under the Income Tax Act, 1961, the benefit you receive upon exercising your stock options is treated as a perquisite under the head ‘Salaries’. The taxable amount is calculated as:
Taxable Perquisite = (Fair Market Value on Date of Exercise − Exercise Price) × Number of Shares
ESOP Perquisite Tax Calculation: A Real Example
Let’s make this concrete with a simple illustration:
Exercise Price: ₹100 per share Fair Market Value (FMV) on Exercise Date: ₹600 per share Number of Shares: 10,000 Taxable Perquisite = (₹600 − ₹100) × 10,000 = ₹50,00,000
This ₹50 lakh is added to your salary income and taxed at your applicable slab rate. For a taxpayer in the 30% slab, the tax liability could be ₹15+ lakh before selling a single share.
Your employer is required to deduct TDS on this perquisite value at the time of exercise. According to guidelines issued by the Income Tax Department (incometax.gov.in), the employer must report this as part of Form 16.
What Is FMV and How Is It Determined for ESOP Taxation?
FMV Fair Market Value is the crux of the entire ESOP tax calculation. The method of FMV determination depends on whether the company is listed or unlisted.
Listed companies: FMV is the average of the opening and closing price on the date of exercise on a recognised stock exchange.
Unlisted companies: FMV must be determined by a Category I Merchant Banker registered with SEBI. The valuation report is critical documentation.
For start up employees, ESOP taxation on unlisted company shares is especially misunderstood. The FMV can be significantly higher than the exercise price even if the company hasn’t gone public creating a paper tax liability with no immediate liquidity to pay it.
Stage 2: Capital Gains Tax When You Sell the Shares
After exercising, when you eventually sell the shares, a second tax event occurs this time under Capital Gains.
The cost of acquisition for capital gains purposes is the FMV on the date of exercise (since that value was already taxed as perquisite).
Short-Term Capital Gains (STCG): If shares are sold within 12 months (24 months for unlisted), gains are taxed at 15% for listed shares.
Long-Term Capital Gains (LTCG): If held beyond the qualifying period, LTCG above ₹1 lakh on listed shares is taxed at 10% without indexation.
For unlisted company shares, LTCG is taxed at 20% with indexation benefits if held for more than 24 months.
Key Takeaways: ESOP Tax Implications in India 2026
1. ESOPs are taxed at two stages: at exercise (as salary perquisite) and at sale (as capital gains).
2. The taxable perquisite = (FMV − Exercise Price) × Shares, and it’s added to your income in the year of exercise.
3. For unlisted startups, FMV is determined by a SEBI-registered merchant banker.
4. TDS is deducted by the employer at the time of exercise.
5. Timing your exercise strategically can significantly reduce your effective tax liability. 6. ESOP capital gains tax depends on the holding period and whether the company is listed or unlisted.
Questions to Ask Before Exercising Your ESOPs
As highlighted by Dr. Haresh Adwani, a PhD in Commerce and legal expert with decades of tax advisory experience, most employees make ESOP decisions without understanding the financial math behind them. Before you exercise, ask:
What is the current FMV and who has certified it?
What will my perquisite tax liability be in this financial year?
Is this a listed or unlisted company, and how does that affect my tax?
Do I have the liquidity to pay the tax before I can sell the shares?
What is the optimal timing strategy to minimize my total tax outgo?
Frequently Asked Questions: ESOP Tax Implications India
Q1. When is ESOP taxed in India at grant, vesting, or exercise?
ESOPs are not taxed at grant or vesting. Tax is triggered at the time of exercise, when the difference between FMV and exercise price becomes a taxable perquisite under the head Salaries.
Q2. How is ESOP perquisite tax calculated for unlisted start up employees?
For unlisted companies, the FMV is determined by a Category I Merchant Banker registered with SEBI. The taxable perquisite is (FMV − Exercise Price) × number of shares, taxed at the employee’s applicable income slab rate.
Q3. Is capital gains tax applicable on ESOPs after sale?
Yes. After exercise, if you sell the shares, capital gains tax applies. The FMV on the exercise date is treated as the cost of acquisition, and gains are taxed as STCG or LTCG depending on the holding period.
Q4. Does the employer deduct TDS on ESOP perquisite?
Yes. The employer is legally required to deduct TDS on the perquisite value at the time of exercise and report it in Form 16. This amount is reflected in your total salary income for the year.
Q5. What is the ESOP tax treatment for unlisted company shares in India 2026?
For unlisted shares, LTCG applies at 20% with indexation if held for more than 24 months; STCG is taxed at slab rates. The FMV must be certified by a SEBI-registered merchant banker for tax purposes.
Conclusion
ESOPs are a genuine wealth-creation tool but only for those who understand the ESOP tax implications in India before making the exercise decision. A poorly timed exercise can generate a tax bill that far exceeds available cash, particularly for start up employees holding unlisted company shares.
The good news: with the right tax planning, you can time your exercise, stagger your sales, and significantly reduce your overall tax burden. The key is knowing the numbers before you act.
Nidhi Adwani is the Human Resources Manager at Adwani & Co. She is a Law Graduate and holds an MBA in Human Resources. She manages recruitment, employee engagement, team development, workplace culture, and the firm’s social media and content activities. Passionate about people and organizational growth, she also contributes articles for ITRAdvisor and Adwani & Co. Her writing focuses on HR practices, leadership, workplace engagement, and professional development, offering practical insights for professionals and businesses.
At ITRAdvisor.in, we help taxpayers with:
✔️ ITR Filing Review
✔️ AIS Reconciliation
✔️ Capital Gains Reporting
✔️ NRI Taxation
✔️ Tax Notice Response
✔️ Revised Returns
✔️ Income Tax Planning
✔️ Refund and Compliance Issues
Visit ITRAdvisor.in today for professional guidance and consultation.
Early action can often prevent bigger tax problems later.
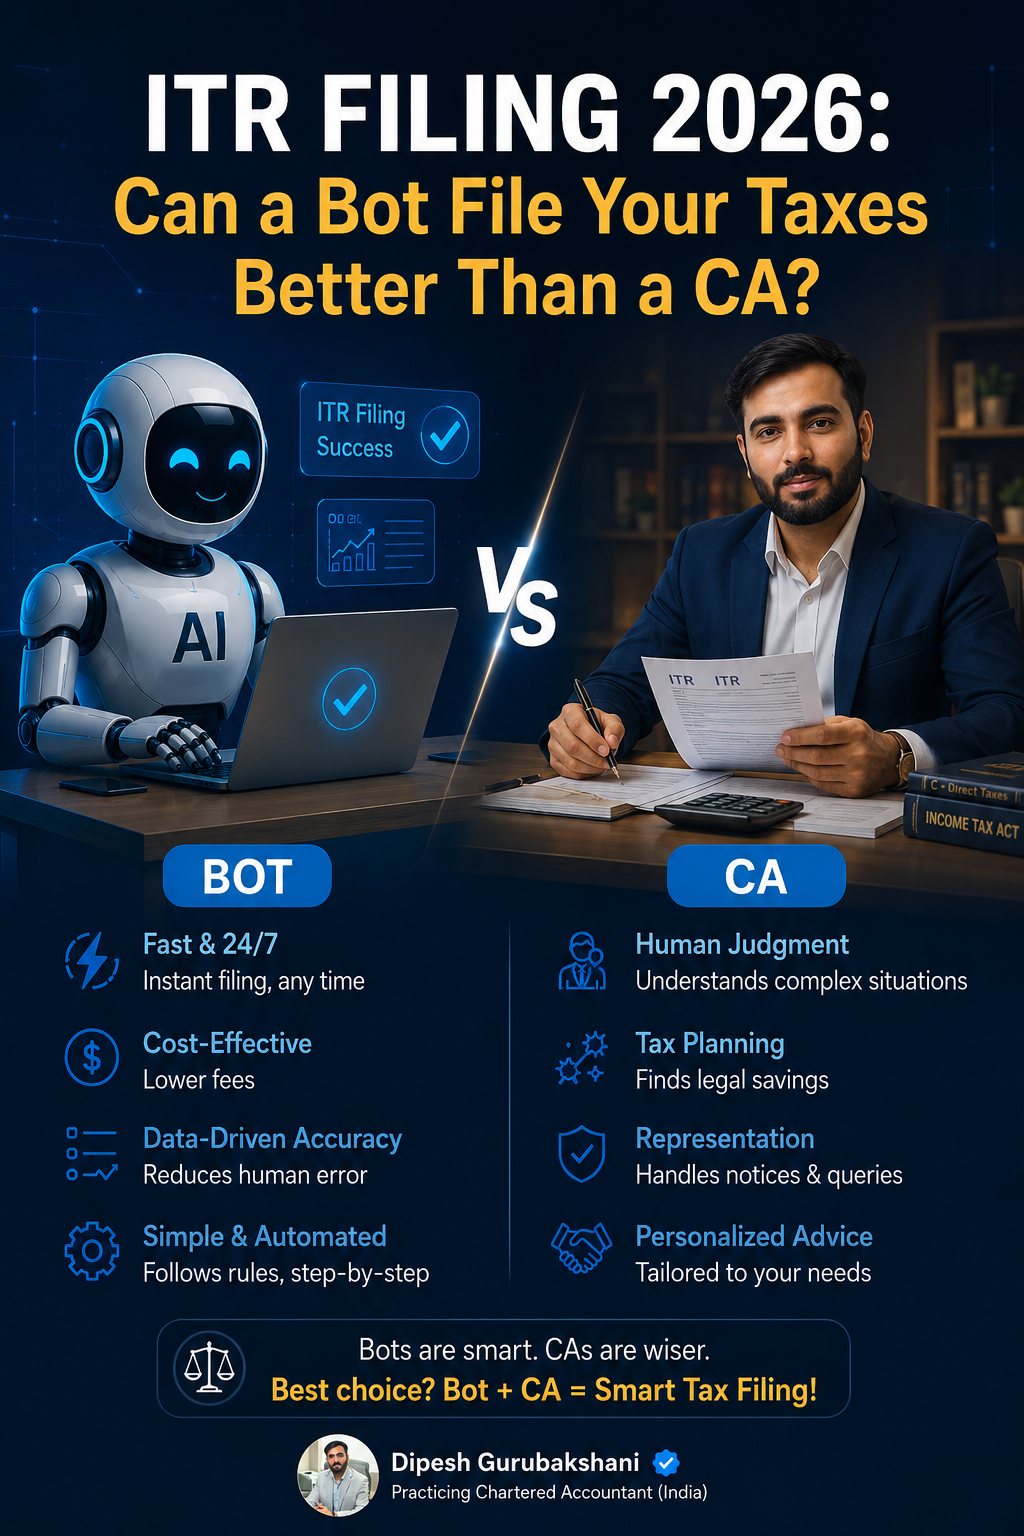
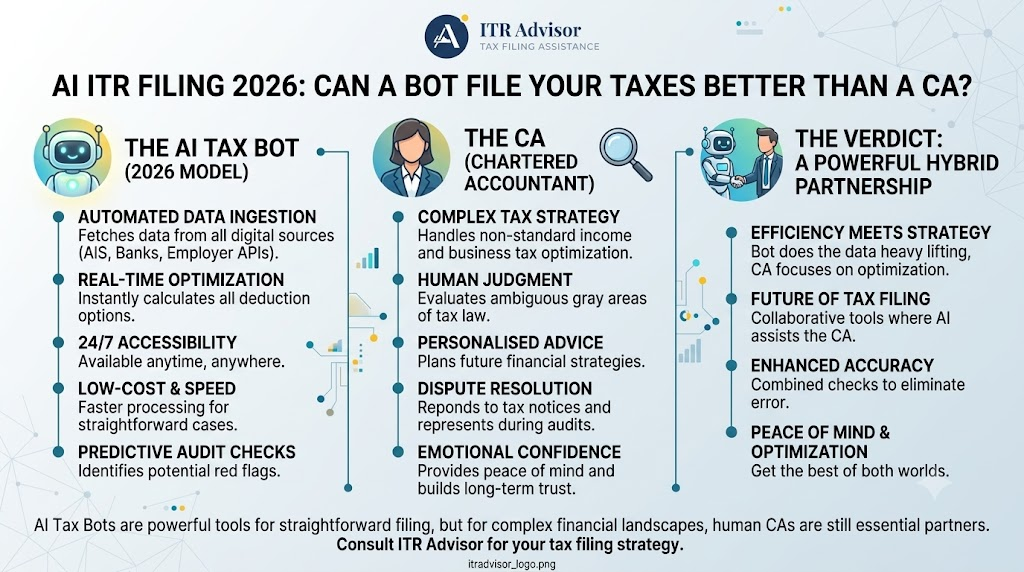
Everyone is asking whether AI can prepare income tax returns. Barely anyone is asking the more important question: who will defend the tax position behind them?
AI ITR filing tools in 2026 are genuinely impressive. They extract data from Form 16 and AIS, pre-populate schedules, flag mismatches with Form 26AS, and generate a draft return faster than any manual process. But here is what they cannot do: determine whether your tax position will hold up if the Income Tax Department sends a notice.
That gap between a technically filed return and a defensible one is exactly what taxpayers need to understand before trusting AI completely with their compliance.
What AI ITR Filing Tools Actually Do Well in 2026
To be fair, AI-assisted tax filing has made meaningful improvements to routine compliance. For straightforward salaried taxpayers with a single employer, Form 16, and standard deductions, AI tools deliver speed and accuracy that was difficult to match manually.
What AI handles reliably in ITR filing 2026:
Auto-fetching pre-filled data from the Income Tax Department’s AIS and Form 26AS
Matching TDS credits with Form 26AS entries to reduce demand notices on mismatch
Suggesting the correct ITR form based on income type — ITR-1, ITR-2, or ITR-4
Computing tax liability under both old and new tax regime and flagging which is lower
Identifying obvious gaps such as a missing TDS entry or an unreported interest income item
Tax risk in India rarely comes from a data extraction error. It comes from reasoning and reasoning is exactly where AI-generated tax returns have a structural gap.
Consider a taxpayer who claims a tax benefit. The numbers are correct. Every document is available. The return passes all system validation checks on the Income Tax Department’s e-filing portal. Yet the questions that matter most remain unanswered:
Questions AI Cannot Answer for Your ITR
→ Is the taxpayer actually eligible for this exemption or deduction?
→ Does a restriction, limitation, or anti-avoidance provision apply?
→ Is there a more advantageous tax position that has not been explored?
→ If the Income Tax Department issues a notice under Section 143(2) or 148, can the position be defended?
These are not rare edge cases. They arise in everyday situations F&O loss set-off against business income, HRA claims without proper rent documentation, deductions under Section 80C with incomplete evidence, or capital gains on equity funds where the holding period is borderline.
The Income Tax Department’s faceless assessment scheme and AI-driven scrutiny systems are specifically designed to catch reasoning inconsistencies not just arithmetic ones. Returns are risk-scored using cross-database matching of ITR data, AIS, GST turnover, MCA filings, and banking transactions. A return that is numerically clean but logically inconsistent across these sources remains a scrutiny risk.
A Real Example: When AI Filed Correctly but Wrongly
Practical Scenario
A freelancer with annual professional receipts of ₹18 lakh used an AI ITR filing tool for AY 2026-27.
The AI correctly:
• Selected ITR-4 (presumptive taxation under Section 44ADA)
• Applied the 50% deemed profit rate declaring ₹9 lakh as income
• Computed tax liability accurately under the new tax regime
What the AI did not evaluate:
• Whether the freelancer had claimed actual expenses exceeding the 50% deemed amount in a prior year, which triggers an obligation to maintain books of account
• Whether certain receipts were from a source that does not qualify under Section 44ADA
Result: The return was filed. But when a scrutiny notice arrived under Section 143(2) querying the presumptive scheme eligibility, there was no documentation trail to support the position. A professional review before filing would have flagged both risks in minutes.
AI ITR Filing 2026 and the Income Tax Notice Risk
As per guidance available through the Income Tax Department’s portal (incometax.gov.in) and CBDT’s risk management framework, cases are increasingly selected for scrutiny based on risk indicators not just mismatches. These indicators include unusual deduction patterns, turnover inconsistencies between ITR and GST returns, and high value transaction disclosures in AIS that do not align with reported income.
In that environment, AI ITR filing 2026 tools create a specific risk: they improve the presentation of a return without improving the underlying defensibility of its positions. A well-formatted, AI-generated return is not automatically a safe return.
This is the reasoning-versus-calculation distinction that tax professionals have been discussing since AI tools entered mainstream compliance and it is the most practically important thing a taxpayer in 2026 needs to understand.
For a detailed breakdown of what triggers income tax notices and how to respond,
What Every Taxpayer Should Remember About AI ITR Filing in 2026
✔ AI ITR filing tools handle data extraction, form selection, and computation well especially for straightforward salaried returns.
✔ The gap is in reasoning: eligibility assessment, deduction defensibility, and position validation.
✔ The Income Tax Department’s faceless assessment and AI-driven risk-scoring evaluate logical consistency not just arithmetic.
✔ Treating an AI-generated ITR as a first draft subject to professional review is the smart approach.
✔ For any non-standard income F&O losses, capital gains, presumptive scheme, foreign income professional review before filing is essential.
Frequently Asked Questions
1. Can AI tools file income tax returns accurately in 2026?
For simple salary-based returns, yes AI tools perform well. For returns involving business income, capital gains, foreign assets, or multiple deduction claims, professional review is strongly recommended before filing.
2. What is the risk of relying only on AI for ITR filing?
The main risk is a reasoning gap AI applies rules mechanically without evaluating whether a specific position is eligible, defensible, or optimal for your situation. This can lead to income tax notices that are difficult to respond to without prior documentation.
3. Does AI ITR filing increase the chance of getting an income tax notice?
Not directly but an AI-filed return that contains an indefensible position is a scrutiny risk regardless of how cleanly it was prepared. The Income Tax Department’s risk-scoring evaluates logical consistency across AIS, GST, and MCA data, not just the arithmetic of the return.
4. Which ITR form should I use for AY 2026-27?
It depends on your income type. ITR-1 is for salaried taxpayers with income up to ₹50 lakh. ITR-2 covers capital gains and multiple properties. ITR-4 applies to presumptive income under Sections 44AD and 44ADA. Read our detailed ITR form selection guide for AY 2026-27 on ITRAdvisor.in.
5. What will be the most valuable tax skill in an AI-driven compliance world?
According to tax professionals including those at Adwani & Co LLP, the highest-value skill will be validating conclusions not just preparing returns. The ability to evaluate whether an AI-generated tax position is legally defensible, commercially reasonable, and consistent with regulatory expectations is what separates a capable tax advisor from a filing service.
Conclusion: AI Is a Tool. Judgment Is the Profession.
AI ITR filing in 2026 is fast, efficient, and accurate on the mechanical layer of compliance. It reduces data entry errors, speeds up return preparation, and makes basic tax filing accessible to a broader audience.
But the most expensive mistakes in taxation are rarely calculation errors. They are reasoning errors wrong eligibility assessments, indefensible deduction claims, and positions that cannot withstand scrutiny. That is where a qualified tax professional still makes the difference that cannot be automated.
The smart approach is not to choose between AI and professional review. It is to use AI for what it does well and ensure a professional reviews what it cannot.
Author
CA. Dipesh Gurubakshani. He is a Chartered Accountant with professional experience in audit, direct taxation, and accounting advisory services.
Whether you have already received a credit card income tax notice or want to ensure you never do Adwani and Company is your trusted partner. Led by Dr. Haresh Adwani and a seasoned team of Chartered Accountants, Adwani and Company provides end-to-end income tax compliance, notice response, and financial planning services.
Get Expert Tax Guidance
If you want to file your ITR accurately and defend it confidently visit ITRAdvisor.in today.
From ITR form selection and tax regime comparison to notice response and professional review, ITRAdvisor.in gives you the tax knowledge you need to stay compliant and avoid costly mistakes
ITRAdvisor.in is an educational and informational platform focused on tax awareness and compliance updates. Nothing contained herein should be construed as solicitation or advertisement of professional services. Professional services, where applicable, are rendered in accordance with ICAI guidelines. This article is published on ITRAdvisor.in, a tax and compliance knowledge platform.
The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP.
Imagine claiming a perfectly legal tax deduction one that the Income Tax Act explicitly allows and having it disallowed by your Assessing Officer simply because he found it suspicious. No evidence. No proof of wrongdoing. Just suspicion. This is precisely the situation that the Income Tax Appellate Tribunal (ITAT) recently pushed back against in a landmark ruling on Section 80GGC deductions, and it has important implications for every Indian taxpayer who has donated to a registered political party.
What Is Section 80GGC? Understanding the Deduction for Political Contributions
Section 80GGC of the Income Tax Act provides a full 100% deduction on contributions made by any person (other than a company or local authority) to a registered political party or an electoral trust. This is one of the few deductions in the Indian tax code that allows complete relief there is no upper ceiling on the deduction amount, subject to the conditions below.
To claim the Section 80GGC deduction, the contribution must satisfy all of the following conditions:
The donor must be an individual, HUF, firm, AOP, or BOI not a company or a local authority.
The contribution must be made to a political party registered under Section 29A of the Representation of the People Act, 1951, or to an electoral trust.
The payment must be made through any mode other than cash. Contributions made in cash are explicitly excluded from the Section 80GGC deduction benefit.
The taxpayer must obtain a receipt from the political party or electoral trust acknowledging the donation.
When these conditions are satisfied, the Section 80GGC deduction is a legitimate and fully supported claim under the Income Tax Act. Disallowing it requires evidence — not conjecture.
The ITAT Ruling: Why Suspicion Alone Cannot Disallow a Section 80GGC Deduction
In a significant ruling that reinforces taxpayer rights, the Income Tax Appellate Tribunal held that mere suspicion on the part of the Assessing Officer (AO) without any concrete, tangible evidence of fraud, bogus payment, or non-compliance with Section 80GGC conditions is legally insufficient to disallow a Section 80GGC deduction claim.
The facts in the case were straightforward: the taxpayer had made a documented, non-cash contribution to a registered political party, claimed the Section 80GGC deduction in the ITR, and produced the relevant receipt. The AO, however, raised doubts about the genuineness of the transaction and disallowed the deduction without examining the political party’s records, without issuing a summons, and without pointing to any specific defect in the documentation.
The ITAT found this approach fundamentally flawed. The tribunal emphasised a principle that runs through Indian tax jurisprudence: the burden of proof lies on the tax department to establish that a claimed deduction is fraudulent or ineligible not on the taxpayer to disprove a suspicion. If the AO had genuine doubts, the correct course was to investigate the political party, verify the receipt independently, or conduct enquiries under Sections 131 or 133(6) of the Income Tax Act. None of that happened. Disallowance of the Section 80GGC deduction was accordingly set aside.
Worked Example: What a Valid Section 80GGC Deduction Looks Like
Parameter
Detail
Taxpayer
Salaried individual, AY 2026-27
Gross Total Income
₹18,00,000
Donation Made To
Registered political party (Sec. 29A, RPA 1951)
Amount Donated
₹2,00,000 (via NEFT)
Receipt
Obtained from the political party
80GGC Deduction
₹2,00,000 (100% of donation, no ceiling)
Net Taxable Income
₹16,00,000 after 80GGC deduction
Outcome If AO Disallows Without Evidence
Appealable at CIT(A) and ITAT — taxpayer likely to succeed per this ruling
What Indian Taxpayers Must Do to Protect Their Section 80GGC Deduction Claim
The ITAT ruling is a relief, but it does not mean taxpayers can afford to be careless with documentation. If your Section 80GGC deduction is questioned, your first line of defence is the quality of your paperwork. Here is what you must have:
Documentation Checklist for Section 80GGC Deduction
Receipt from the registered political party or electoral trust specifically acknowledging the donation amount, date, and your PAN.
Bank statement or payment proof showing the NEFT/cheque/digital transfer cash donations are entirely ineligible under Section 80GGC.
Confirmation that the party is registered under Section 29A of the Representation of the People Act, 1951 you can verify this through the Election Commission of India’s published list.
Copy of your ITR showing the Section 80GGC deduction has been correctly entered in Schedule VI-A.
If your Section 80GGC deduction is disallowed despite clean documentation, you have a strong appellate case, as this ITAT ruling demonstrates.
Key Takeaways: Section 80GGC Deduction and the ITAT Ruling
• Section 80GGC allows a 100% tax deduction on contributions to registered political parties or electoral trusts with no upper limit.
• Cash donations are completely ineligible. All 80GGC contributions must be made through banking channels.
• The ITAT has ruled that an AO cannot disallow a Section 80GGC deduction based on suspicion alone concrete evidence of non-compliance is required.
• The burden of proving that a deduction is bogus lies with the tax department, not the taxpayer.
• Maintain a receipt from the political party, bank transfer proof, and ITR Schedule VI-A entry to defend any 80GGC disallowance. • If your Section 80GGC deduction is wrongly disallowed, you can appeal to CIT(A) and then ITAT, where this ruling significantly strengthens your case.
Expert Perspective: Proving Legitimacy Is About Documentation, Not Debate
Dr. Haresh Adwani, a PhD in Commerce and tax practitioner associated with ITRAdvisor.in, puts it plainly: ‘The Section 80GGC deduction is one of the most straightforward claims in the Indian tax code 100% of a non-cash donation to a registered party, fully deductible. The problem arises not from the law but from poor record-keeping. Taxpayers who maintain a clear paper trail receipt, bank proof, PAN linkage rarely face sustained disallowance. The ITAT has now confirmed what we have always advised: suspicion is not a substitute for evidence, and taxpayers need not accept a disallowance that lacks legal foundation.’
What to Do If Your Assessing Officer Disallows Your Section 80GGC Deduction
If you receive a draft assessment order or a final order disallowing your Section 80GGC deduction without adequate grounds, your escalation path is clear:
File your objections with the Dispute Resolution Panel (DRP) if applicable, or file an appeal before the Commissioner of Income Tax (Appeals) [CIT(A)] within 30 days of receiving the demand order.
Cite this ITAT ruling in your appeal submissions to demonstrate that suspicion alone is legally insufficient for Section 80GGC disallowance.
Attach all documentation receipt, bank statement, ITR schedule as annexures to your appeal memorandum.
If the CIT(A) also rules against you, escalate to the ITAT, where the position on evidence-based disallowance is now well-established.
Do not simply pay a demand arising from an unjustified Section 80GGC disallowance. The appellate system exists precisely for these situations, and taxpayers who engage it with proper documentation generally prevail.
Q1. Who is eligible to claim a Section 80GGC deduction?
Any individual, HUF, firm, AOP, or BOI can claim the Section 80GGC deduction. Companies and local authorities are explicitly excluded from this provision.
Q2. Is there a maximum limit on the Section 80GGC deduction?
No. Section 80GGC allows a 100% deduction with no upper ceiling on the amount contributed to a registered political party or electoral trust, provided the payment is non-cash.
Q3. Can my Assessing Officer disallow the Section 80GGC deduction without evidence?
As per the ITAT ruling discussed in this article, a disallowance based purely on suspicion without evidence is not legally tenable. The AO must establish specific non-compliance to disallow the deduction.
Q4. Where do I enter the Section 80GGC deduction in my ITR?
The Section 80GGC deduction is entered in Schedule VI-A of ITR-1, ITR-2, ITR-3, or ITR-4 (as applicable), under the heading ‘Deductions under Chapter VI-A’.
Q5. What happens if I made a cash donation to a political party? Can I still claim Section 80GGC?
No. Section 80GGC explicitly bars deductions for cash donations. Only contributions made through banking channels (NEFT, cheque, UPI, demand draft) qualify for the deduction.
Conclusion: Know Your Rights Under Section 80GGC and Claim Them Confidently
The ITAT’s ruling on Section 80GGC deduction disallowance is a powerful reaffirmation of a fundamental principle: in India’s tax system, as in law more broadly, suspicion is not proof. If you have made a legitimate, documented, non-cash contribution to a registered political party and your Assessing Officer disallows the Section 80GGC deduction on vague grounds, you have both the right and the legal precedent to fight back.
What protects you is not complicated it is a receipt, a bank statement, and a correctly filed ITR. If you have those, your Section 80GGC deduction stands on solid ground. If it is still challenged, the appellate route is well-established and, as this ITAT ruling shows, increasingly taxpayer-friendly where documentation is clean.
Claimed a Section 80GGC deduction and received a disallowance notice?
ITRAdvisor.in provides clear, authoritative guidance on all income tax deductions, ITAT rulings, and notice responses. Whether you need to understand your Section 80GGC eligibility, respond to a scrutiny notice, or appeal an unjust disallowance, our resources will walk you through every step.Visit ITRAdvisor.in today — because a legally correct claim deserves a legally correct outcome.
About the Author:
Mukesh Chavan is a dedicated indirect taxation and compliance professional associated with Adwani & Co LLP, specializing in GST advisory, GST audits, GST assessments, and RERA compliance services. With extensive experience in handling complex regulatory matters, he assists businesses in ensuring compliance with evolving GST laws and real estate regulations while minimizing risks and enhancing operational efficiency.
Mukesh has successfully guided clients through GST registrations, return compliance, departmental assessments, audits, litigation support, and tax planning strategies. He also possesses significant expertise in RERA compliance, helping real estate developers, promoters, and stakeholders navigate regulatory requirements and maintain seamless project compliance.
Through his articles and professional insights, Mukesh aims to simplify complex GST and RERA provisions, offering practical guidance that empowers businesses to remain compliant, avoid disputes, and make informed decisions in an increasingly dynamic regulatory environment. His approach combines technical expertise with practical business understanding, enabling clients to focus on growth while meeting their statutory obligations with confidence.
Not Sure If Your Return Is Clean? If you’re unsure whether your return has been reported correctly, a quick review today can help avoid a much bigger problem later. If you want expert guidance, connect with itradvisor.in today.
Need Help Before You File? If you’re a salaried professional, business owner, freelancer, or NRI and want to ensure your ITR matches your AIS and Form 26AS before submission — ITRAdvisor.in is where to start. Visit itradvisor.in for expert tax guidance, AIS reconciliation checklists, and professional support backed by Adwani & Co LLP.
Disclaimer
ITRAdvisor.in is an educational and informational platform focused on tax awareness and compliance updates. Nothing contained herein should be construed as solicitation or advertisement of professional services. Professional services, where applicable, are rendered in accordance with ICAI guidelines. This article is published on ITRAdvisor.in, a tax and compliance knowledge platform. The content has been reviewed for technical accuracy by professionals associated with Adwani & Co LLP.
ITR Filing Below ₹2.5 Lakh: Is It Really Mandatory?
Many taxpayers assume that if their annual income falls below the basic exemption limit of ₹2.5 lakh, income tax return filing simply doesn’t apply to them. This belief, while common, can be costly. The truth is more nuanced and in several situations, ITR filing below 2.5 lakh income is not just advisable, it is legally mandatory under the Income Tax Act, 1961.
Understanding the Basic Exemption Limit vs. ITR Filing Obligation
The ₹2.5 lakh figure represents the basic exemption limit under the old tax regime the income level below which, in most ordinary cases, no tax is payable. However, the obligation to file an income tax return below the taxable limit is governed by a separate set of conditions under Section 139(1) of the Income Tax Act, and these conditions override the simple “no tax, no filing” assumption.
In other words, having income below 2.5 lakh tells you about your tax liability, not necessarily about your filing requirement. These are two distinct legal questions, and conflating them is one of the most frequent and avoidable mistakes taxpayers make.
When ITR Filing Becomes Mandatory Despite Low Income
Under the seventh proviso to Section 139(1), income tax return filing is mandatory for individuals even with income below the taxable limit if any of the following apply during the financial year:
Mandatory ITR Filing Triggers (regardless of income level)
• Deposited ₹1 crore or more (cumulatively) in one or more current bank accounts
• Spent ₹2 lakh or more on foreign travel for self or any other person
• Paid electricity bills exceeding ₹1 lakh in a year
• Total sales, turnover, or gross receipts of business exceed ₹60 lakh
• Gross receipts from a profession exceed ₹10 lakh
• TDS and TCS during the year is ₹25,000 or more (₹50,000 for senior citizens) • Deposits in one or more savings bank accounts total ₹50 lakh or more
If any of these conditions are met, ITR filing for income below taxable limit becomes compulsory under law, irrespective of whether actual tax liability is nil. Non-compliance can attract penalties under Section 234F and scrutiny notices from the Income Tax Department.
Why Voluntary ITR Filing Makes Sense Even When Not Mandatory
Beyond the legal triggers, there are strong practical reasons to consider voluntary ITR filing below 2.5 lakh income even when none of the above conditions apply:
Benefits of Filing ITR Even With No Tax Liability
• Claim TDS refunds deducted on bank interest, fixed deposits, or freelance payments
• Build a verifiable income record for visa applications, loans, and credit cards
• Carry forward capital losses or business losses to set off against future income
• Serve as proof of income for government tenders, scholarships, and subsidies • Avoid last-minute compliance pressure if your income crosses the threshold mid-year
Practical Guidance from a Tax Professional
In Dr. Haresh Adwani’s experience advising individual taxpayers across Pune and beyond, the most common red flag is high-value cash deposits or foreign travel spending that taxpayers don’t realise pushes them into mandatory filing territory, even though their taxable income remains nil. A quick review of your AIS (Annual Information Statement) on the income tax portal before the deadline can flag these triggers early and prevent unnecessary notices.
The Income Tax Department’s e-filing portal and the AIS/TIS framework now cross-verify high-value transactions automatically, making it increasingly difficult to overlook these obligations. Staying proactive, rather than reactive, is the safest approach to ITR filing compliance in 2026.
Key Takeaways
• Income below ₹2.5 lakh does not automatically exempt you from filing an ITR
• Always check your AIS/TIS before assuming no filing is required • When in doubt, consult a qualified tax professional before the ITR filing deadline AY 2026-27
Generally no, but it becomes mandatory if you meet specific high-value transaction conditions like large bank deposits or foreign travel spending.
2.Can I claim a refund without filing ITR if my income is below the exemption limit?
No, filing an income tax return is the only way to claim a TDS refund, even when your income is below 2.5 lakh.
3.What happens if I don’t file ITR despite meeting a mandatory trigger?
You may face penalties under Section 234F and could receive a scrutiny notice from the Income Tax Department.
4.Does filing ITR help even with zero tax liability?
Yes, it builds an income record useful for loans, visas, and carrying forward losses for future tax benefits.
Conclusion: File Smart, Stay Compliant
ITR filing below 2.5 lakh income is governed by more than just the basic exemption limit specific transaction-based triggers under Section 139(1) can make filing mandatory regardless of your tax liability. Even where filing isn’t compulsory, doing it voluntarily protects your financial interests and keeps your compliance record clean.
Nidhi Adwani is the Human Resources Manager at Adwani & Co. She is a Law Graduate and holds an MBA in Human Resources. She manages recruitment, employee engagement, team development, workplace culture, and the firm’s social media and content activities. Passionate about people and organizational growth, she also contributes articles for ITRAdvisor and Adwani & Co. Her writing focuses on HR practices, leadership, workplace engagement, and professional development, offering practical insights for professionals and businesses.
At ITRAdvisor.in, we help taxpayers with:
✔️ ITR Filing Review
✔️ AIS Reconciliation
✔️ Capital Gains Reporting
✔️ NRI Taxation
✔️ Tax Notice Response
✔️ Revised Returns
✔️ Income Tax Planning
✔️ Refund and Compliance Issues
Visit ITRAdvisor.in today for professional guidance and consultation.
Early action can often prevent bigger tax problems later.